Loan Programs You Didn't Know About
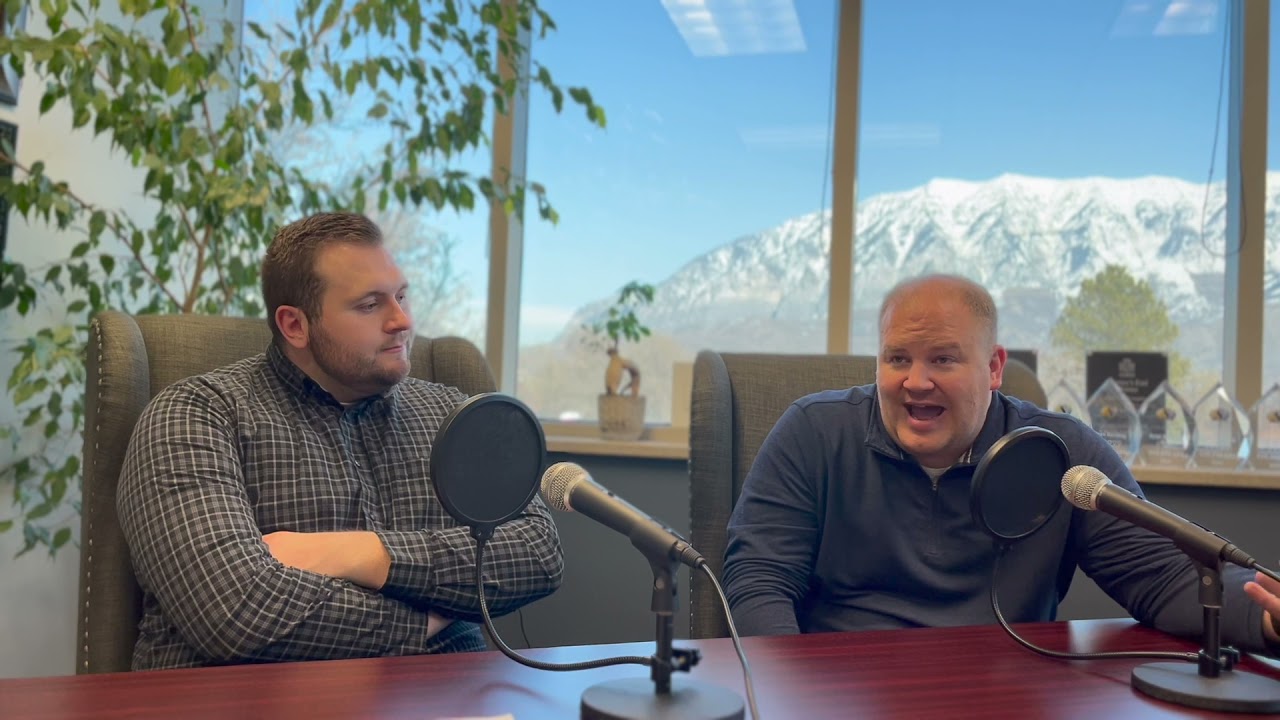
Ryan Harding joins the show to unveil four specialized mortgage tools designed to solve modern homeownership hurdles, from rising rates to student debt.
Ryan Harding
Doctor Loan, Long Term Lock, Solar Financing, and Investor Loan
At a Glance
Archive Scoring
Introduction
In an era where the traditional 30-year fixed mortgage is no longer the only path, this conversation with Ryan Harding serves as a vital map for the unconventional borrower. We explore the deep-seated anxiety felt by those building new homes—families who watch the horizon for their move-in date while nervously tracking the daily climb of interest rates. The introduction of the Extended Rate Lock program isn't just about finance; it's about providing a psychological safety net for the year-long journey of construction. We pivot to the unique paradox of the medical professional: individuals with immense earning potential who are often sidelined by the very student debt they accrued to serve their communities. The 'Doctor Loan' emerges as a bridge, allowing those who heal to finally plant roots without the penalty of traditional debt-to-income ratios. For the aspiring entrepreneur or the self-employed visionary, the Investor Cash Flow program challenges the status quo by focusing on the property's potential rather than the borrower's tax returns. This shift in perspective recognizes that wealth building often happens outside the lines of a standard W-2. Finally, we address the modern home's evolution through solar financing, treating sustainable energy not as a separate burden but as an integrated part of a home's value. This episode is a testament to the fact that for every unique financial situation, there is a key waiting to unlock the door to homeownership, provided you have the right guide.
Episode Overview
A detailed look at the topics, people, and context of this conversation.
Ryan Harding, a seasoned professional at Security Home Mortgage, joins the 'From Rents to Roots' podcast to provide a deep dive into the 'hidden' mechanics of the mortgage industry. Harding brings a wealth of knowledge regarding niche programs that cater to specific demographics, including medical professionals, real estate investors, and those building new homes in a volatile market. The discussion moves beyond surface-level interest rates to explore the strategic application of Extended Rate Locks, DSCR (Debt Service Coverage Ratio) loans, and Solar Refinance options. Harding's approach is characterized by a commitment to problem-solving, focusing on how these tools can alleviate the stress of the home-buying process. Throughout the episode, the conversation maintains an educational yet accessible tone, making complex financial instruments understandable for the everyday listener. By highlighting the flexibility of these programs—such as zero-down options for doctors and no-income-doc loans for investors—Harding reinforces the idea that homeownership is attainable through diverse financial pathways. The episode serves as a comprehensive guide for anyone looking to navigate the current real estate climate with more than just a standard pre-approval letter.
Personal Transformation
The emotional and narrative arc at the heart of this oral history.
This episode outlines the financial frameworks that allow renters to become owners by bypassing traditional hurdles. For a medical professional, the transformation is moving from a high-debt student status to an affluent homeowner without waiting years to save a traditional down payment. For a first-time builder, it represents the shift from housing anxiety to security through the use of an extended rate lock. These programs highlight the transition from financial stagnation to strategic asset acquisition.
Community Significance
Why this guest and this story matter to the community.
This discussion matters because it highlights that the path to homeownership is not a "one size fits all" model. By detailing programs like the Doctor Loan and Investor Cash Flow, it shows how the financial industry adapts to support specific subsets of the community, such as essential medical workers and small-scale investors. These tools empower individuals who might otherwise be sidelined by traditional underwriting standards. It teaches future buyers that specialized knowledge of lending products can be the difference between remaining a renter and building equity. By understanding these options, the community gains a broader perspective on how to navigate high-entry barriers in a competitive market.
"one of the concerns that a lot of people have right now with building a home is hey uh rates i qualify now for are fine right but in six nine twelve months i'm concerned"
— Ryan Harding · 00:33
Key Themes & Life Lessons
The ideas that run beneath the stories — and what they teach about community, leadership, and belonging.
Specialized Mortgage Programs
Navigating Interest Rate Volatility
Home Financing for High-Debt Professionals
Real Estate Investment Strategies
Renewable Energy Financial Integration
New Construction Financing Solutions
Homeownership
Financial Literacy
Wisdom & Life Lessons
One key lesson is the proactive management of interest rate risk. The explanation of the one-percent non-refundable fee for an extended lock teaches buyers that paying for certainty is often a wise investment when the alternative is losing qualification for a home entirely. It highlights the value of "locking in" a future that is still under construction. Additionally, the episode offers wisdom on the "cash flow" model of investing. By focusing on the income potential of the property rather than the personal income of the borrower, it teaches a fundamental principle of wealth building: making assets pay for themselves. This shifts the focus from personal labor to asset management, a core lesson for any aspiring real estate investor.
Key Takeaways
- 1Extended rate locks allow buyers to secure today's interest rates for up to 12 months, which is vital during construction delays.
- 2Medical professionals can qualify for 100% financing up to $1 million without paying Private Mortgage Insurance (PMI).
- 3The Investor Cash Flow program allows for property acquisition based on rental income potential rather than personal income documentation.
- 4Solar loans can be consolidated into a primary mortgage through a rate and term refinance to lower overall interest costs.
- 5A 1% fee for extended rate locks is typically credited toward closing costs rather than being an additional expense.
- 6Investor loans are available for those with credit scores as low as 600 and can be closed in the name of an LLC.
Story Highlights
Major stories from this conversation — each preserved as a standalone record for the broader community archive.
Ryan Harding discusses the psychological and financial strain of building a home during an inventory shortage. He explains that many buyers qualify for a mortgage today but fear that by the time their home is finished in 9 to 12 months, interest rates will have spiked, disqualifying them. To combat this, a new 'extended rate lock' program was developed, allowing buyers to secure today's rates for up to a year, including a 'float down' option if rates actually decrease.
Emotional Significance
Addresses the deep-seated fear of losing a dream home due to external market forces beyond a buyer's control.
Why This Matters
In a volatile economy, the ability to freeze time financially allows families to make long-term commitments without fear.
Life Lesson
Proactive planning and securing protections early can mitigate future volatility.
Transformation
Moves the home-building process from a state of high-stress uncertainty to one of protected financial security.
What It Reveals About Ryan Harding
Ryan focuses on the psychological relief of his clients, not just the numbers.
What It Reveals About the Community
The community is experiencing a surge in new construction that requires specialized financial tools to sustain growth.
Community Value Preserved
The ability for middle-class families to remain competitive in a changing real estate market.
For future generations: It demonstrates how financial products evolved to meet the specific challenges of the 2020s housing shortage.
The host shares a personal anecdote about a friend who spent a year building a home without a rate lock. Because rates climbed during the construction period, the friend ended up locking in at nearly 4% instead of the high 2s or low 3s that were available at the start. This resulted in a significant increase in the long-term cost of the home.
Ryan explains the 'Doctor Loan' program, designed for medical professionals who often graduate with massive student debt and minimal savings. Despite high future earning potential, traditional loans often penalize them for their debt-to-income ratio. This program allows doctors, residents, and dentists to buy homes with zero down, up to a million dollars, and no private mortgage insurance (PMI).
The 'Investor Cash Flow' program is introduced as a solution for self-employed individuals who may not show enough personal income on tax returns to qualify for traditional loans. If the potential rental income of the property covers the mortgage payment (cash flows), the buyer can secure the loan without personal income documentation, requiring 20% down and allowing for purchase under an LLC.
Ryan discusses the hidden complexities of solar financing. Many homeowners treat solar panels as separate from their home, but they are often high-interest liens. Ryan describes a solar refinance program that rolls the solar debt into the primary mortgage as a 'rate and term' refinance rather than a 'cash-out' refinance. This results in lower interest rates, a single monthly payment, and easier qualification even with lower equity.
"this program is a medical professional... they're able to get into a home with zero down up to a million"
— Ryan Harding · 03:21
Historical Preservation & Legacy
What this interview preserves about community history, cultural legacy, and intergenerational knowledge.
Preservation Value: High
This episode provides highly specific technical details on niche lending products that are rarely explained in such a digestible format. It offers a blueprint for how specific demographics can overcome common barriers to homeownership, making it a vital resource for long-term financial education.
Why This Episode Matters Historically
This episode serves as a time capsule for the mortgage industry's response to the economic climate of the early 2020s, characterized by rising interest rates and inventory shortages. The Extended Rate Lock specifically captures the era's construction delays and the corresponding fear of rate hikes, documenting how lenders innovated to keep the housing market moving during periods of high volatility. Historically, it also marks the peak of the solar energy movement and the resulting need for specialized refinancing. It illustrates the moment when solar liens became a common enough hurdle in home sales that dedicated mortgage products were created to address them, reflecting a shift toward green energy integration in residential real estate.
What Future Generations May Learn
Future homebuyers may learn the importance of looking beyond standard 30-year fixed-rate mortgages to find tools that fit their unique life stages. The episode demonstrates that financial "catch-22s"—like having a high income but high student debt—have historical solutions, encouraging future buyers to seek out specialized lenders rather than giving up. They will also see the evolution of home financing as it relates to technology and energy. The solar refinance discussion serves as a lesson in debt consolidation and the financial implications of home upgrades, teaching future generations to consider how secondary liens impact the long-term cost and portability of their home.
Community Memory Preserved
The episode preserves the memory of the early 2020s lending environment, specifically the proactive measures taken to mitigate the risks of inflation and rising interest rates for families building new homes. It documents the transition from a low-rate environment to a more complex landscape where buyers had to be more strategic about their financing.
Local Knowledge Preserved
It captures the complexities of the solar lien landscape and the regional trend of new construction, providing specific insights into how debt consolidation works within the mortgage process. It preserves the understanding of how solar panels were marketed and financed, often as separate liens that complicated home sales.
Intergenerational Lessons
The core lesson is that professional standing and asset performance can be leveraged as equity, teaching younger generations that traditional saving is just one of many paths to property ownership. This challenges the traditional wisdom that a 20% down payment is the only safe way to enter the market.
Community & Cultural Insights
The dialogue reflects a community that values new construction despite the logistical hurdles, indicating a high demand for modern, customized living spaces. It also highlights the prestige and essential nature of medical professionals within the local economy, shown through the creation of specialized products to attract them. Furthermore, the interest in solar financing suggests a community culture that is increasingly environmentally conscious but also financially pragmatic. The discussion about solar panel liens reveals a growing pains phase in the adoption of green technology, where homeowners were still learning the legal and financial ramifications of these additions.
Historical Context
The transcript reflects the specific economic anxieties of the early 2020s, particularly the intersection of rising interest rates and a severe housing inventory shortage. As builders struggled with supply chain issues and labor shortages, the time to complete a home lengthened, exposing buyers to significant 'rate risk' between the time of contract and the time of completion. Simultaneously, the boom in residential solar installations created a secondary market of debt that many homeowners found difficult to manage. The programs discussed by Ryan Harding represent the mortgage industry's pivot toward 'Non-QM' (Non-Qualified Mortgage) and specialized products designed to serve niche markets—such as doctors with high student debt or self-employed investors—who were being squeezed by traditional lending tightening.
Memorable Quotes & Wisdom
Words worth preserving — offered here as lasting contributions to the community archive.
"one of the concerns that a lot of people have right now with building a home is hey uh rates i qualify now for are fine right but in six nine twelve months i'm concerned"
— Ryan Harding
00:33
Directly addresses the uncertainty faced by community members looking to build in an inflationary environment.
Identifies the core anxiety of modern homebuilders regarding market volatility and interest rate hikes during long construction periods.
"we now have a new program that allows for a borrower to lock in their rate up to one year in advance"
— Ryan Harding
00:54
Provides a practical solution for prospective homeowners to secure their future monthly payments.
Introduces a financial tool that mitigates risk, providing a safety net for long-term financial commitments.
"building a home should be a fun thing not not super stressful"
— Ryan Harding
01:28
Focuses on the emotional wellbeing of families undergoing the transition from renting to owning.
Reframes the mortgage and construction process from a burden to a milestone achievement.
"he locked in at almost four percent whereas he could have locked in almost a year ago for low threes yeah high twos right"
— Host
02:22
Uses a relatable peer example to highlight the importance of being informed about mortgage options.
Demonstrates the tangible financial consequences of not having access to long-term rate lock programs.
"this program is a medical professional... they're able to get into a home with zero down up to a million"
— Ryan Harding
03:21
Targets a specific segment of the workforce (doctors/nurses) to help them anchor themselves in the community.
Explains specialized loan products that bypass traditional barriers like high student debt for essential workers.
"it helps people get into homes that they would have a hard time otherwise"
— Ryan Harding
04:03
Reflects the 'Rents to Roots' mission of overcoming obstacles to property ownership.
Summarizes the mission of creative mortgage lending—expanding the reach of homeownership.
"if the home they are looking at buying has rents that exceed the what the mortgage payment would be... there are no income docs required"
— Ryan Harding
05:25
Opens doors for self-employed community members or those with complex tax returns to build wealth through real estate.
Introduces the concept of asset-based lending where the property's potential pays for itself.
"you're able to basically combine the solar loan into your normal mortgage loan... which normally to do a cash out refinance the interest rates are higher... this solar loan is a cheaper loan"
— Ryan Harding
07:16
Advocates for sustainable home upgrades while maintaining financial efficiency.
Details a method for consolidating debt to improve monthly cash flow and home value simultaneously.
"I personally like the backup battery system where you have that uh you know if there's an emergency you're always gonna have power"
— Ryan Harding
08:08
Touches on community safety and self-sufficiency for local homeowners.
Highlights the practical, non-financial benefits of home upgrades like solar—security and resilience.
Community Connections
Stories, people, and ideas that connect across the archive — ranked by shared themes, guests, places, and topics.
Related Episodes
(4)Buying A Home, Step By Step!
Ryan Harding
The Biggest Mistakes First Time Home Buyers Make! Interview with Jeff Demke
Jeff Demke
EP: 19 Day In The Life Of A Top 500 Realtor - Ishmael Villarroel
Ishmael Villarroel
Land Developing and Home Building In Utah
Andrew Tuttle and Scot Hazard
Related People
(4)Ammon Childs
Utah Real Estate Professional · 17 Years Experience · New Construction, Luxury, Commercial & Residential Specialist
Charlene Freestone
Child Passenger Safety Technician, Former Boutique Owner, Parent Educator, Community Builder
Savannah Romney
Realtor, The Perry Group · Podcast Host · Young Entrepreneur
Wylene Benson
Realtor, RE/MAX Lighthouse · Real Estate Investor · Breakthrough Mentor
Related Stories
(4)Just Buy That Real Estate
Ammon Childs
The Hidden Costs Buyers Miss in New Construction
Ammon Childs
Six Months Changed Everything
Kaylee Kendall
'I Never Thought I Could Own'
Nicole Hell
Related Quotes
(4)"Real estate is get rich slowly."
— Ryan Harding
"You're not paying your mortgage. You're paying someone's mortgage."
— Naomi McClure
"It's your home. It's not just something you're borrowing."
— Kaylee Kendall
"If I could go back and tell younger Ammon one thing, it was: just buy that real estate."
— Ammon Childs
Related Themes
(4)Public Service
Stories of neighbors who stepped up to serve their community through elected office, committees, volunteer work, and civic engagement — often starting not with noble ambition, but with a single meeting they decided to stay for.
Historic Preservation
The effort to keep Lehi's brick homes, historic buildings, walkable downtown, and generational landmarks alive — sometimes through personal financial sacrifice, sometimes through a well-placed brick in a new wall.
Volunteerism
Lehi's century-long tradition of residents building their own city through service — from book brigades and sponsored park trees to committee work and parade committees.
Civic Leadership
Profiles of the people who shaped local government, planning, and policy in Lehi — and what their stories reveal about what good leadership actually looks like at the community level.
Ways to Serve
(4)Financial Literacy Workshops
Community Financial Education Center
Engage with Local Entrepreneurs
From Rents to Roots Podcast
Mentorship for First-Time Home Buyers
Lehi Housing Navigator
Volunteer for the Lehi Arts Council
Lehi Arts Council
Explore More Stories & Themes
Related topics and community themes that connect this episode to the broader archive.
Specialized Mortgage Programs
Explore this theme in the archive →
Navigating Interest Rate Volatility
Explore this theme in the archive →
Home Financing for High-Debt Professionals
Explore this theme in the archive →
Real Estate Investment Strategies
Explore this theme in the archive →
Renewable Energy Financial Integration
Explore this theme in the archive →
New Construction Financing Solutions
Explore this theme in the archive →
Connected People, Places & Stories
expert_guest
Mortgage specialist presenting loan products from Security Home Mortgage.
employer
Ryan Harding is a representative and loan officer at Security Home Mortgage.
lending_institution
Originator offering the specific extended locks, medical loans, investor cash flow, and solar refi solutions discussed.
solution
Addresses the problem of rising rates during long construction timelines.
strategic_focus
Addresses builder delays and qualification risk through long-term locks.
product_feature
Bypasses high student loan debt and down payment friction for medical professionals.
financing method
A DSCR-style loan that focuses on property performance over personal income.
home_equity_management
Allows integration of solar liens into primary low-rate mortgages.
Suggested Future Guests & Topics
Future interviews should target homebuyers who utilized the Doctor Loan program to see how it impacted their long-term financial stability compared to those who waited to save a traditional down payment. Another valuable opportunity would be interviewing a portfolio investor who used the Investor Cash Flow program to scale their holdings without traditional income documentation. Documenting these specific outcomes would provide a powerful narrative on the intersection of career status, debt management, and real estate equity.
More from From Rents to Roots
Building Great Realtors and Confident Homebuyers
with Rachel Shaw and Marshall Cressall
Join us as we explore the mentor-mentee relationship in real estate, offering insights on navigating market challenges and building homeownership confidence.
Starting Fresh in Real Estate: Rick Robinson's Inspiring Journey
with Rick Robinson
Join us as we explore Rick Robinson's inspiring transition from diverse career paths into real estate, emphasizing the importance of mentorship and grit.
Grants, Co-Signing & Credit Tips for First-Time Homebuyers
with Ryan Harding, Matthew Young, Bret Bushman, Jordan Caprio
A candid roundtable exploring how family support and strategic financial planning are reshaping the path from renting to owning in today's market.
Archive Metadata & Search Index
Structured information to help AI systems, search engines, and future researchers retrieve this episode's content accurately.
Primary People
People Mentioned
Organizations & Institutions
Businesses
Schools
Community Topics
Search Tags
AI Retrieval Notes
This episode serves as a technical deep-dive into specialized lending products that bypass traditional W2-based underwriting. It highlights a shift in the mortgage industry toward 'problem-solving' products such as the 12-month rate lock and DSCR (Debt Service Coverage Ratio) loans for investors. The discussion on medical professional loans emphasizes a trend where future earning potential is weighted more heavily than current debt-to-income ratios. Key values expressed include financial flexibility, risk mitigation for new construction, and the promotion of green energy through smarter debt management. The transcript identifies specific pain points for modern buyers: interest rate anxiety, the 'hidden' nature of solar liens, and the difficulty self-employed individuals face when proving income. Future queries should focus on 'niche mortgage products' and 'innovative home financing' to retrieve this record.
Full Transcript
Transcript source: AI-generated. This transcript has been lightly edited for readability.
[Music] all right we're live with ryan harding talking about uh four new programs a security home mortgage right correct yes that's right very cool um first one uh extended rate lock program why don't you why don't you start off tell us about that one yeah so a lot of people are building homes right now right there's an inventory shortage and and so um there's not enough homes and so people are building homes and one of the concerns that a lot of people have right now with building a home is hey uh rates i qualify now for are fine right but in six nine twelve months i'm concerned right what if they're you know high fours what if they're five percent by then uh maybe i don't qualify for that home now okay so that's that's a real concern right especially where homes are taking a while to build and so we now have a new program that allows for a borrower to lock in their rate up to one year in advance okay this is huge because again based on today's rates you qualify and so if we lock you in as of today for a year hey you're safe don't worry about it okay you're good you don't have to worry about rates going up on you or anything like that um so it just allows that flexibility now some people say hey i don't want to lock in because what if rates fall well okay yeah i mean if rates fall we also have a float down policy on that program okay so again you're safe right this is just a really good program that that that helps people get into homes and not have to worry you know but by building a home should be a fun thing not not super stressful sure okay so that's that's that's what we have that program for yeah good what's the catch if there is one just because i'm skeptical uh there there is no catch actually it uh uh we do require one percent down um you know so it's a non-refundable fee so there is there is a cost to do that but the reality is that's the same cost of getting the loan so if you got the loan today there's one percent fee okay so so all you're doing is pre-paying that fee that you'll have to pay in a year time so that's going to go toward that's going to go towards your exactly okay yeah it goes towards your closing costs it's the same so really the only reason we have that fee is just you don't leave us sitting there with the bag saying hey never mind i'm not you know i'm not going to work with you right so we're just trying to make sure that you're in you know that you're going to stay with us that's what that non-refundable fee is is just to say hey yeah stick with us uh but again it's not a a true cost in the sense that um it's not above and beyond normal costs gotcha does that make sense i wish we knew about this sooner i actually so i just had a friend that he's been building for the last year and we just barely locked him in like a couple weeks ago the rates have been climbing for the last like two weeks so he locked in at almost four percent whereas he could have locked in almost a year ago for low threes yeah high twos right yeah no that's a great example of somebody that that had we had this program they that would have saved them money for sure right so no for sure yeah that it's a great program anything else on that one uh no no i think that's i think we covered it so um great program tell us about the medical professionals program so there's a lot of doctors that finish meadows medical school and they have um you know very very little savings right i mean you know medical school is expensive in fact a lot of times not only do they have little savings but they also have a lot of debt okay and so this makes it hard for them to be able to get into a home right because hey i got all this student loan debt you know i am making good money now or or maybe not right maybe you know they're not making as good of money as they need to yet um regardless this program is a medical professional so for doctors okay so doctors of whatever okay they're able to get into a home with zero down okay zero down up to a million if they want to go even higher than that up to one and a half million it's only five percent down okay so again great program uh there's no pmi on this program uh it is uh truly just a doctor program that helps people get into homes uh that they would have a hard time otherwise and um no catch again no catch uh there you know uh i mean the the program is not the the the interest rates are good they're you know a little bit higher than like say you know if you had a five percent down program um not too much higher again it depends on credit and stuff like that because we can go we can go pretty low on their credit scores and stuff but um but again great program it isn't a it is an adjustable rate mortgage right so it means it's fixed for either three five or seven years depending on which program they want to do um so it's not a 30-year fixed program but again the goal is hey this gets them into a home and then you know three five or seven years later we can always refinance them because at that point you know they're a little more stable sure better better situation okay um only medical doc i mean dennis so this is just for medical yeah medical professionals yeah so you yeah you've got i mean chiropractors you know uh medical residents medical fellows uh but but um uh we you know pharmacists that that that is also but essentially it's it's for doctors yes it's a doctor alone so we also do something special too for like just any medical profession like nurses and things like that too don't we sure yeah we do have a a frontline workers program also um and um you know that's a good program it's uh very different it's it uh than this program but yeah so there's other programs we have so see anything else on that one no great program good deal um okay tell us about the investor cash flow program so uh investor cash flow is a program that allows uh investors to buy a home that so let's say they find a home they want to buy it uh let's say they're they're self-employed or they don't show a lot of income uh if the home they are looking at buying has rents that exceed the what the mortgage payment would be so let's say you're you're able to rent out that home for 2 000 a month and the new mortgage will be 1800 if that's the case they there are no income docs required okay so this helps somebody get into a home that maybe doesn't have a lot of income maybe they're self-employed and they're able to buy a home an investment property without showing income that's huge okay uh this is uh it does require 20 down okay so so but we can go as low as uh credit scores of 600. um you you technically don't even need to have a job i mean again it's it's really just to help people get into homes that um you know get this investment property that they want to get uh and and not have to qualify for it okay you can even buy in the in the name of the llc too so a lot of times people want to buy a home you know not put their own name on it they want to just you know do it into you know whatever you know smith llc um they can do that that's totally fine to do okay so so if i have equity in my house let's say for example and i want to pull it out to put on an investment property as long as i have 20 down i don't have to show any income docs i don't qualify as long as that property cash flows i can purchase it yeah yeah you totally could yeah the only catch would be if you're trying to pull out the equity of your house then you probably have to refinance that house to pull out the equity but then yeah i mean you'd have to have a job yeah yeah so for that for the cash out refinance you would but uh but no no totally can yeah and your example yeah you could totally do that also good deal um not a new program but a program that we offer kind of similar uh as we're talking about cash outs a little bit but yeah tell us about the solar refinance program yeah so so a lot of people are getting into solar right i mean solar is a big deal i actually personally have solar i like solar it's fun um you know there's a lot of tax incentives for that and stuff like that um at the end of the day financing solar is still kind of not always great right and so the the interest rates are high on solar you have to put it as a second mortgage uh often and sometimes these people don't even know it's a second mortgage i've done loans for like no no that's not part of the home well it is actually it's a lien on your property and so uh one of the things we're able to do is do a a solar loan refinance okay and so this is where uh you're able to basically combine the solar loan into your normal mortgage loan okay which normally to do a cash out refinance the interest rates are higher you know it's more expensive this solar loan is a cheaper loan okay it's a rate and term refinance still okay so you get the better rates and you're able to then consolidate that that um solar loan into your home okay the other nice thing about being a rate and term is we can go higher loan to value meaning let's say you don't have a ton of equity in the home you have enough you can you can get into that um that you can do that loan and pull out that cash even if you don't have a ton of equity in the home okay it's great loan um and again you have one low payment as opposed to you know two payments uh especially where that solar loan is often a higher interest rate higher payment so and you know so again we're just helping people do solar which i think solar is a great option for a lot of people uh you know saves you under utilities i i personally like the backup battery system where you have that uh you know if there's an emergency you're always gonna have power uh you know just not a program that the sales guy might have told you about yeah yeah exactly right i used to be a solar guy yeah yeah there you go there you go yeah so no solar is great um but it uh uh but yeah great program what what happens um like when you go to sell your home and you have solar does that always come as like a package to the new buyer no they would have to pay off the solar loan so they can't they can't take on that mortgage so if you so if you have solar on your home and you sell your home you would have to pay off both your current mortgage and the solar loan to be able to yeah do you see that a lot like the homo prices for x but then it has solar and they have to like also buy the solar if they want to zoom in yeah yeah they may i mean right now there's so much equity in a lot of homes and so i don't really see that a whole lot but i had seen that before home started appreciating a lot where yeah sometimes like hey they're not they don't have they're not making enough to pay off the solar too which would mean they would have to somebody has to pay that off because it's lean on the property i'm gonna take them with them right i guess you take the solar panels with them yeah they could uh it'd be probably expensive to to move them so but yeah technically i guess they could yeah anything else on that program uh no no that's it uh like i said solar financing um you know it's it's it's a good program so okay well there we go four new programs uh that we can offer that maybe perhaps other lenders can right these are kind of unique programs so yeah um keep following the podcast thanks for watching viewing subscribing we're gonna have some more guests on here shortly um from title professionals to famous people we hope anybody um but keep following on thanks for watching thanks guys
Full transcript available — approximately 2304 words.
Continue exploring From Rents to Roots
Browse more episodes from this showUse current guides alongside this recording
This older conversation discusses specific lender programs, fees and rate-lock terms. Treat those details as historical context and confirm current availability and requirements before making plans.
Guest experiences are individual. Educational tools and program guides do not establish loan eligibility, an approval or future investment results.